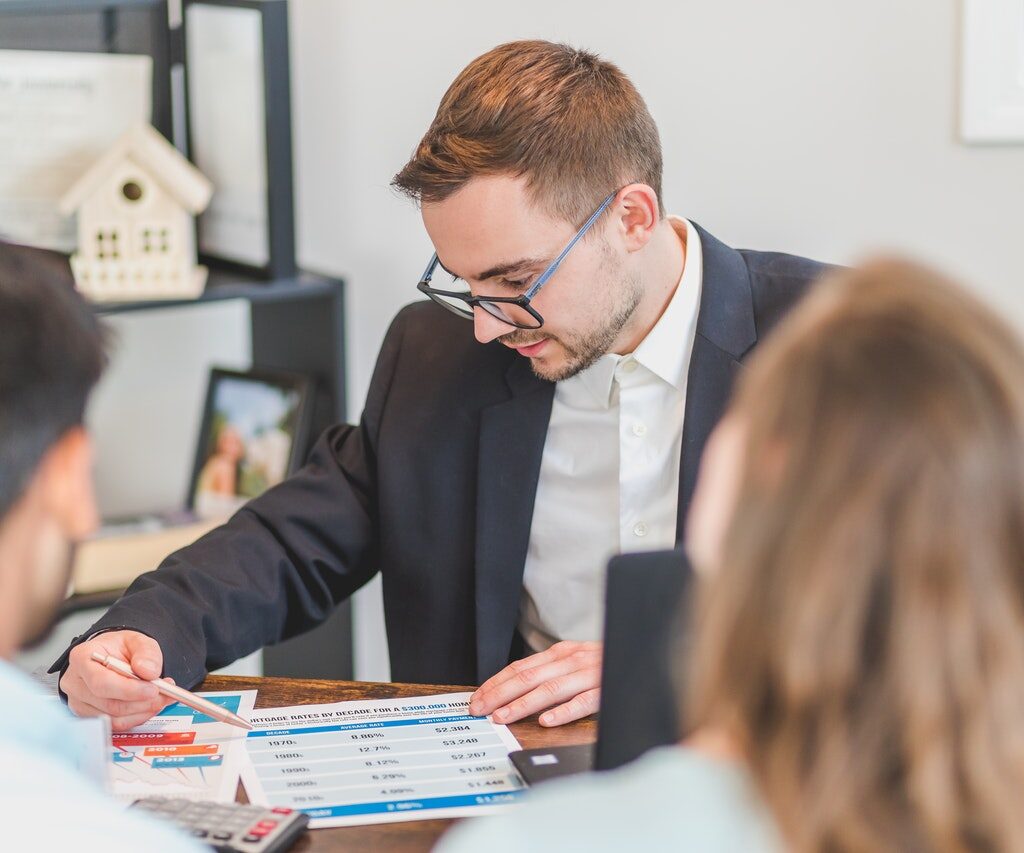
For most Canadians, purchasing a home is a substantial financial investment. A mortgage pre-approval is an essential step in the home-buying process. It is an evaluation by a lender of your creditworthiness and ability to repay a loan. A pre-approval can give you an idea of how much money you can borrow and can make you a more competitive buyer in the housing market.
Read on to discover what to do for a successful mortgage pre-approval in Canada.
Check Your Credit Score
Your credit score is one of the most critical factors in getting a mortgage pre-approval. A credit score is a numerical representation of your creditworthiness. Lenders use this score to determine whether you qualify for a loan and what interest rate you will pay. It is recommended that you check your credit score before applying for a pre-approval to ensure there are no errors or discrepancies. You can obtain a free credit report from Equifax or TransUnion in Canada.
Provide Proof of Income
Lenders want to know that you have a steady income to repay a loan. You will need to provide proof of income, such as pay stubs, T4 slips, or tax returns. If you are self-employed, you may need to provide additional documentation, such as financial statements or business tax returns. It is essential to have all of this documentation prepared before applying for a pre-approval.
Calculate Your Debt-to-Income Ratio
Your debt-to-income ratio is the percentage of your monthly income that goes towards paying off debt. Lenders use this ratio to determine how much money you can afford to borrow. It is recommended that your debt-to-income ratio be no more than 36%. To calculate your ratio, add up all of your monthly debt payments and divide them by your gross monthly income. If your ratio is too high, you may need to pay down some debt before applying for a pre-approval.
Save for a Down Payment
Most lenders require a down payment when purchasing a home. The down payment is a percentage of the purchase price of the home that you pay upfront. The minimum down payment in Canada is 5% for homes valued at $500,000 or less and 10% for homes valued at $500,000 to $1 million. If the home is valued at more than $1 million, the minimum down payment is 20%. It is recommended that you save for a down payment before applying for a pre-approval to show lenders that you are committed to purchasing a home.
Choose the Right Mortgage Broker
A mortgage broker is a professional who can help you find the right mortgage product for your needs. They work with multiple lenders to find the best rates and terms for you. It is essential to choose a mortgage broker who is licensed and experienced in the Canadian market. You can ask for referrals from friends and family or research online for reputable brokers.
Conclusion
A mortgage pre-approval is an important step in the home-buying process in Canada. It can give you an idea of how much money you can borrow and make you a more competitive buyer in the housing market. To get a pre-approval, you will need to check your credit score, provide proof of income, calculate your debt-to-income ratio, save for a down payment, and choose the right mortgage broker. By following these tips, you can increase your chances of getting a mortgage pre-approval and finding the home of your dreams.
Are you looking for a mortgage specialist in Ottawa? Ottawa Mortgage Services is here to help you secure the right mortgage for your needs. Contact us today!